The Partnership Gap
If your partner died tomorrow, who would own half your company?
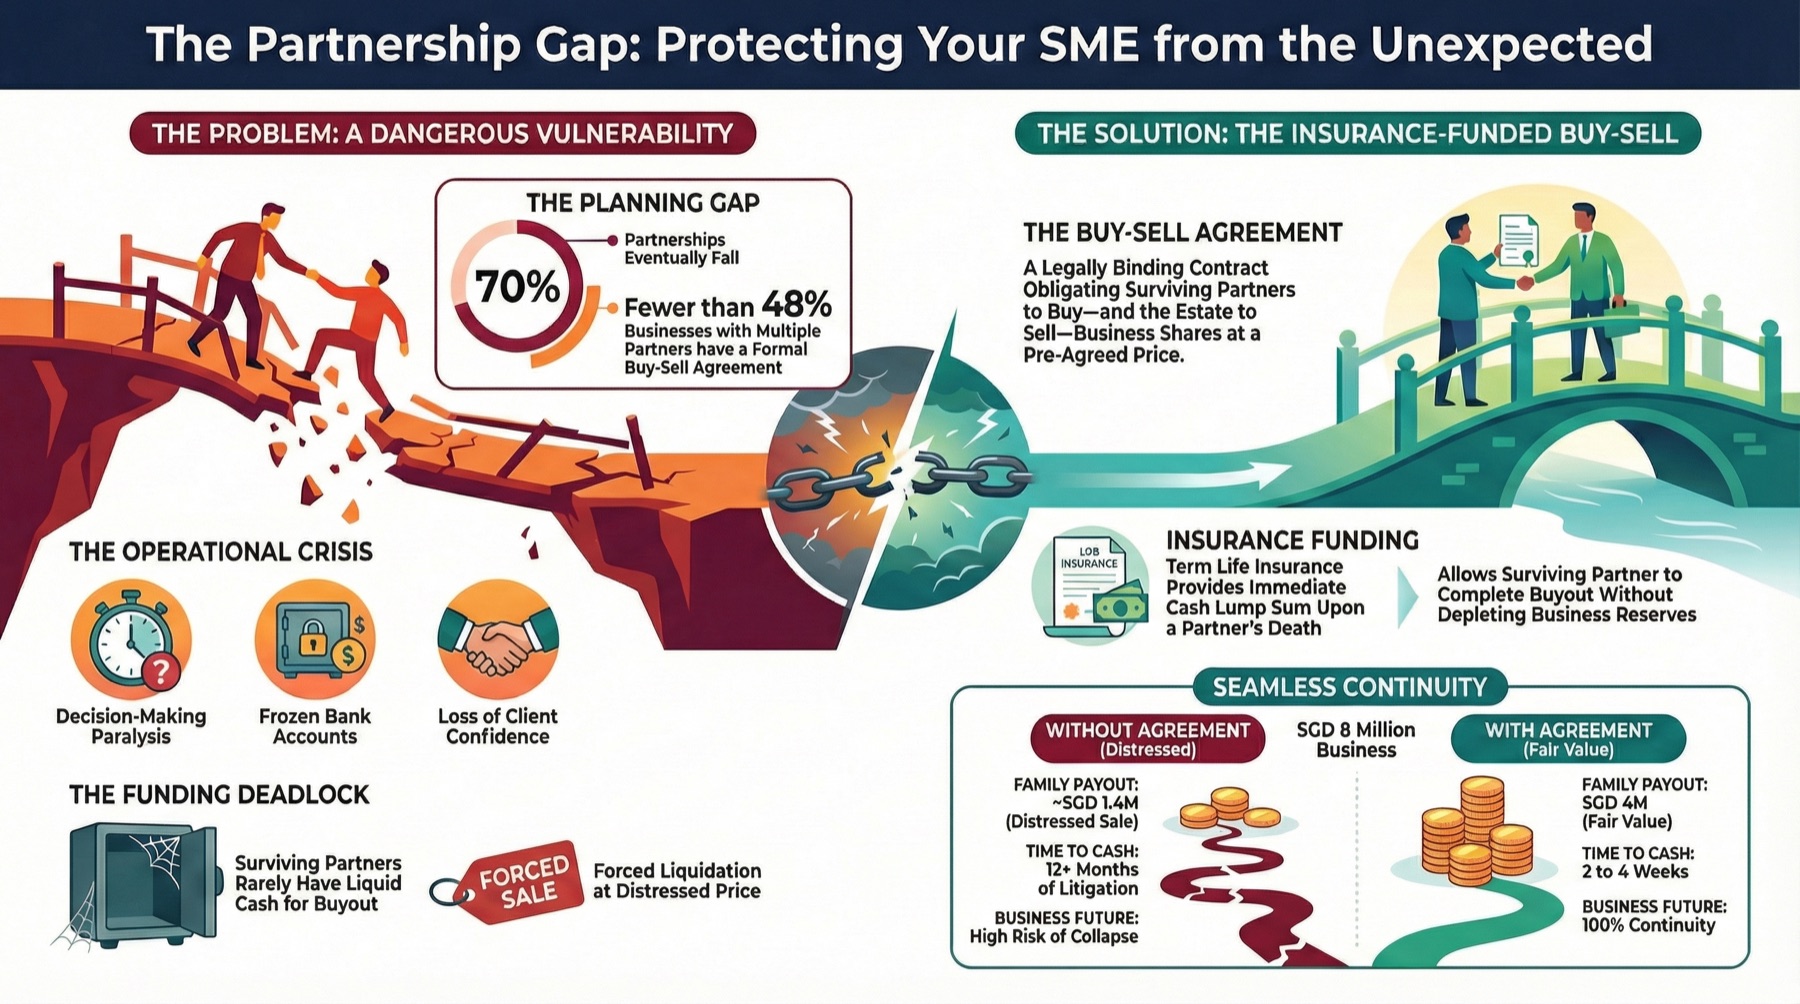
Most SME owners have never asked that question. Their partner's shares pass to the family, the surviving partner can't raise the cash to buy them, and a business built over 20 years can fall apart in one. A buy-sell agreement, funded properly, prevents that.
Get the free white paperThe gap most partnerships never close
Owners plan for growth, tax and retirement. Very few plan for the day a partner is gone.
Sources: Exit Planning Institute; Singapore Department of Statistics; studies cited in the white paper. recheck before launch
One business, two endings
ABC Trading is worth SGD 8 million. David and Michael each own half. At 55, David dies of a heart attack. Here is what happens next.
Without a buy-sell agreement
The family gets about SGD 1.4M, after a year or more.
- Week 1David's shares pass to his wife, Sarah. She has never worked in the business.
- Months 1–3Board decisions stall. Key clients leave. The bank reviews the credit line.
- Months 3–6Michael can't raise SGD 4M. Both sides hire lawyers. Revenue drops 25%.
- Months 6–12Senior staff resign. Talks break down.
- Year 1+The business is sold at a distressed SGD 3.5M. Everyone loses.
With an insurance-funded agreement
The family gets SGD 4M within about four weeks.
- Week 1The agreement is triggered. Michael files the insurance claim.
- Weeks 2–4The policy pays SGD 4M. Michael buys David's shares at the agreed price.
- Months 1–2Sarah has the full value in cash. The share transfer is done.
- AfterMichael runs the business with full control. Clients and staff stay. The families stay on good terms.
| Without | With | |
|---|---|---|
| Family receives | ~SGD 1.4M | SGD 4M |
| Time to cash | 12+ months | 2–4 weeks |
| The business | Forced sale | Carries on |
An illustration based on the case in the white paper. Names and figures are hypothetical.
How a buy-sell agreement works
It is less complicated than most owners expect.
Agree the rules
The partners sign an agreement: if one of us dies or becomes permanently disabled, the others buy the shares, and the family sells them, at a price set in advance.
Fund it
Each partner is insured for the value of their shares, so the cash is there on the day it is needed. No borrowing, no fire sale.
Review it
The value and the cover are checked as the business grows, so the agreement keeps up with what the business is worth.
The whole picture on one page
Listen: surviving the death of a business partner
A 17-minute conversation about what really happens, and how owners protect themselves.
Get the free white paper
Written for owners of established SMEs in Singapore and Malaysia.
- The Partnership Gap, the full white paper (20 pages)
- Partnership Protection, the 15-page illustrated guide
- A conversation with a licensed adviser about your own business, if you'd like one
Your adviser
to come
Alex Lee
Personal finance advisory and business protection specialist. Alex works with business owners to structure business continuity, partner protection and family security, so the company survives unexpected events and families are not financially affected.
licence title, rep number and firm name from Alex
This page is for general information only. It is not financial, legal or tax advice and does not take your personal circumstances into account. Advice on insurance products is given only by a licensed financial adviser representative.
Published by Arters Pte Ltd, Singapore. yitpeng@arters.sg